
What Is a Positively Geared Property?
A positively geared property is one where the rent it earns is more than the total cost of owning it. In other words, after you pay the loan interest, rates, insurance, management and upkeep, there is money left over. That leftover is positive cash flow, and it lands in your pocket rather than coming out of it.
Positive gearing is simply the state of being in that position. A negatively geared property runs at a loss each year, so you cover the gap yourself. A positively geared property runs at a profit, so it supports you while you hold it.
Positive Gearing vs Negative Gearing: What Is the Difference?
The difference comes down to one thing: does the rent cover the costs, or not? Negative gearing means the costs are higher than the rent, so the property loses money each year, and you claim that loss against your other income at tax time. Positive gearing means the rent is higher than the costs, so the property makes money, and you pay tax on the profit.
Neither is automatically better. Negative gearing suited a market where prices rose quickly, because the yearly loss was small next to the growth. Positive gearing suits a market like 2026, where income is certain and growth is slower. The table below sets them side by side.
| Feature | Positively geared | Negatively geared |
|---|---|---|
| Rent vs costs | Rent is higher than costs | Costs are higher than rent |
| Yearly cash flow | Puts money in your pocket | Comes out of your pocket |
| Tax position | You pay tax on the profit | You claim the loss against income |
| Effect on borrowing | Protects your borrowing power | Can shrink your borrowing power |
| Suits investors who want | Income now, and to keep buying | Growth, with cash to cover the gap |
There is also a tax angle worth watching. The May 2026 Federal Budget proposes to wind back negative gearing on established homes from 1 July 2027, while eligible new builds keep their concessions. We covered that in our guide to the 2026 Budget negative gearing changes. None of that detail is law yet, so please treat it as general information rather than tax advice.
How Do You Know If a Property Is Positively Geared?
You work it out with one simple test: take the annual rent, then subtract every cost of holding the property, including the loan interest. If the number is above zero, the property is positively geared. If it is below zero, it is negatively geared.
Here is a worked example, and every figure is an estimate. Say a new-build home costs $650,000, and you borrow $585,000 at around 6.5% interest, which is roughly $38,000 a year. Run as a standard rental at $560 a week, it earns about $29,120 a year, so after interest and about $10,000 of other costs it runs at a loss. Now run the same home as a co-living layout at around $1,000 a week. It earns about $52,000 a year, which is an EST. 8.0% gross yield. After the same $48,000 of total costs, it clears about EST. $4,000 a year before tax, and more once depreciation is counted. That is the difference a configuration makes.
So the rent figure alone never tells the whole story. What matters is the rent left over after the costs, and that is the number to ask for before you buy.
What Are the Benefits and Trade-Offs of Positive Gearing?
The main benefit is income. A positively geared property supports itself, so you are not funding it from your salary each month, and that spare cash can go toward the next deposit. Just as importantly, it protects your borrowing power. Lenders count strong rental income in your favour, which is why a cash-flow property helps you keep buying, while a string of loss-making ones can stall you.
The trade-off is tax and, sometimes, growth. Because a positively geared property makes a profit, you pay tax on that profit rather than claiming a loss. And the very highest yields often sit in smaller towns with thinner demand, so a big number on its own is never the full picture. The aim is a strong, reliable income in a place people actually want to rent.
Want to know whether a property would actually pay for itself? A quick call is the easiest place to start.
Book a quick callHow New Builds Reach Positive Cash Flow
Most standard houses do not reach positive cash flow at today’s rates, because one rent against a full mortgage rarely covers the costs. New builds change that in three ways. First, configuration. A dual-key or co-living layout earns more rent from the same block, which is what lifts a 4% house toward an EST. 8% return. Second, depreciation. A brand-new build lets you claim the building and fittings against your income, which improves the after-tax result. Third, rent. New homes attract the strongest market rent and the lowest vacancy.
That is why we focus on new, income-first stock rather than chasing a postcode on a list. As a general guide, a dual-key layout on one title sits around an EST. 4.7% to 6.5% yield, while a co-living layout can reach an EST. 8.0% to 10.5%. You can see how the numbers work on the dual occupancy homes we cover here, and on the co-living properties explained here.
Here are current co-living homes from our stock, all at Uptown Estate in Shepparton, Victoria. Each one is brand new, full turnkey, single-storey, and sits on a 1,080m² block, and each comes with the builder’s 75% five-year rental guarantee. They rent by the room, which is what lifts the yield from a standard house rate toward the numbers below. Every figure is an estimate.
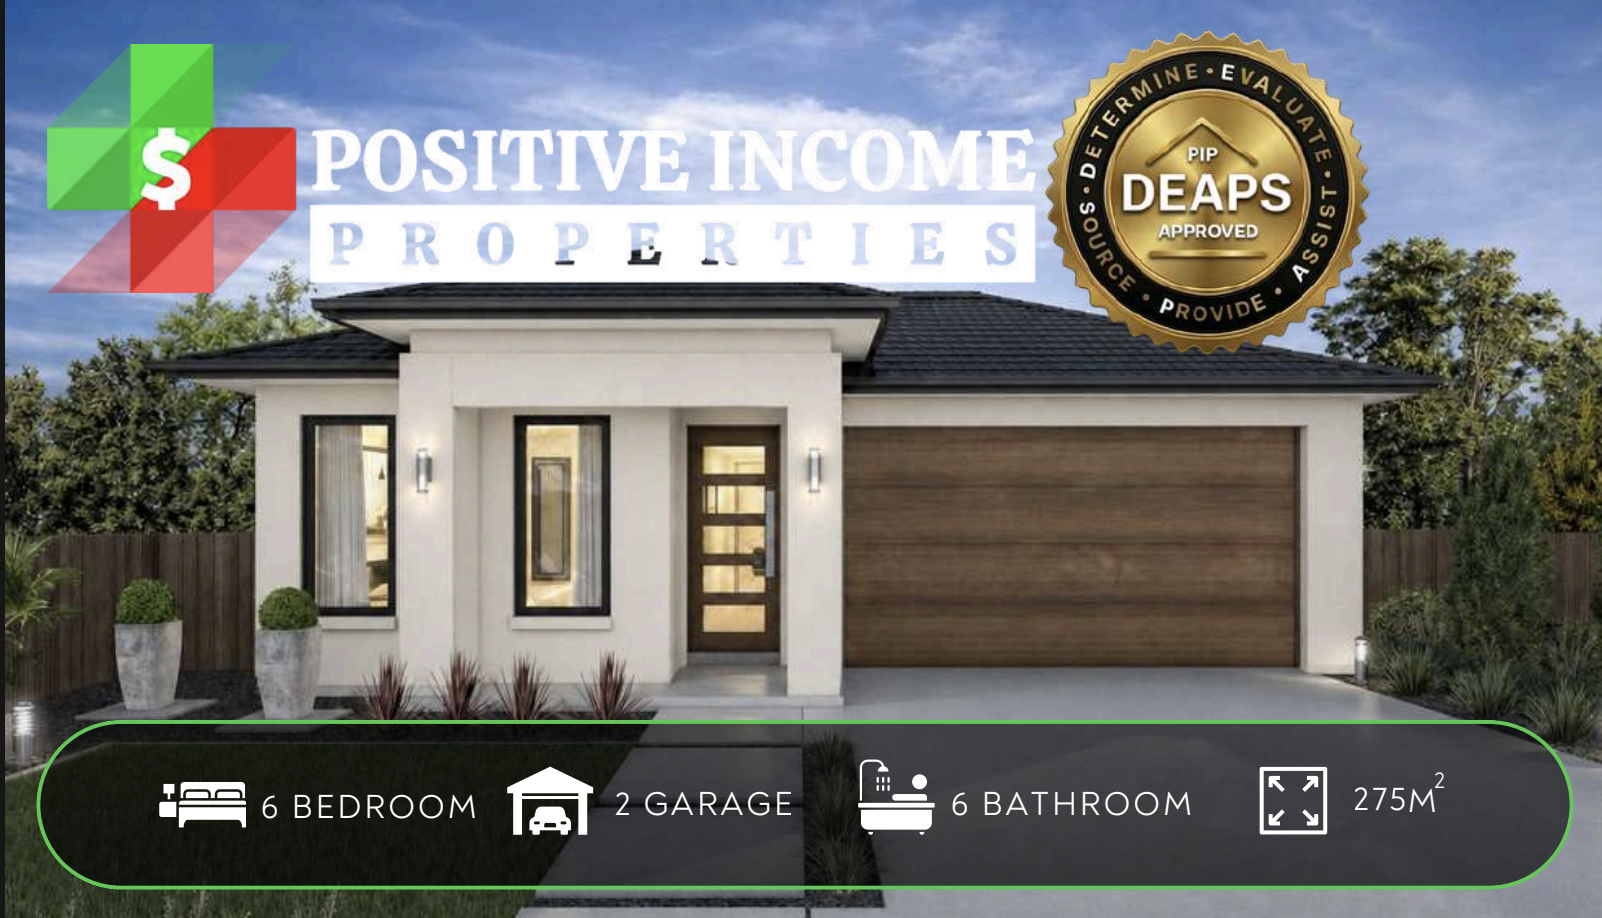
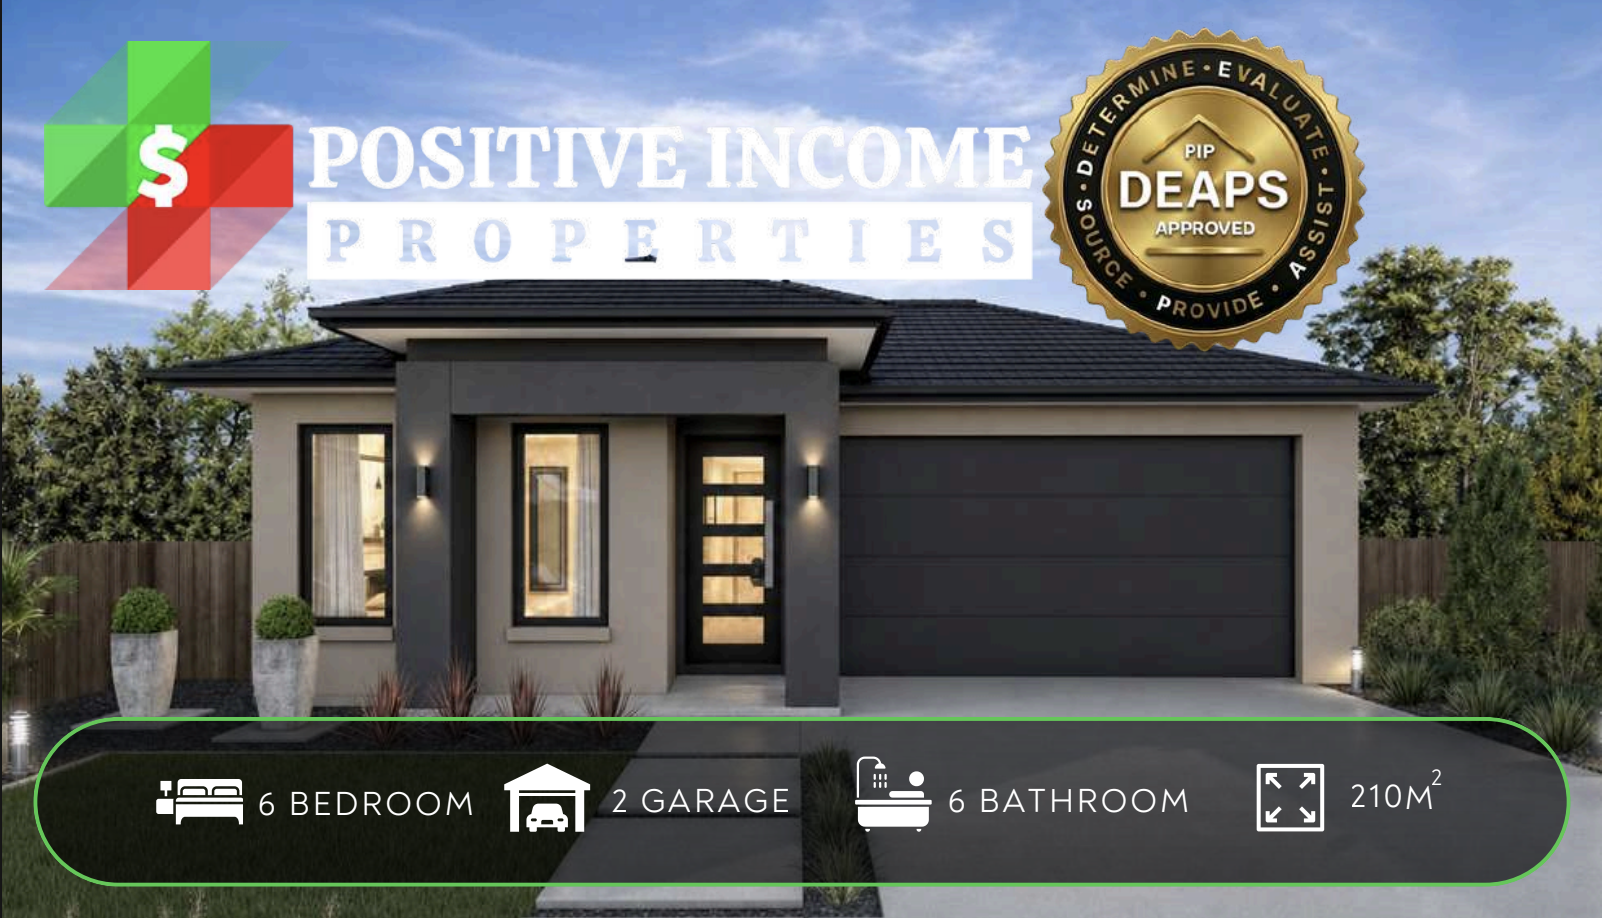
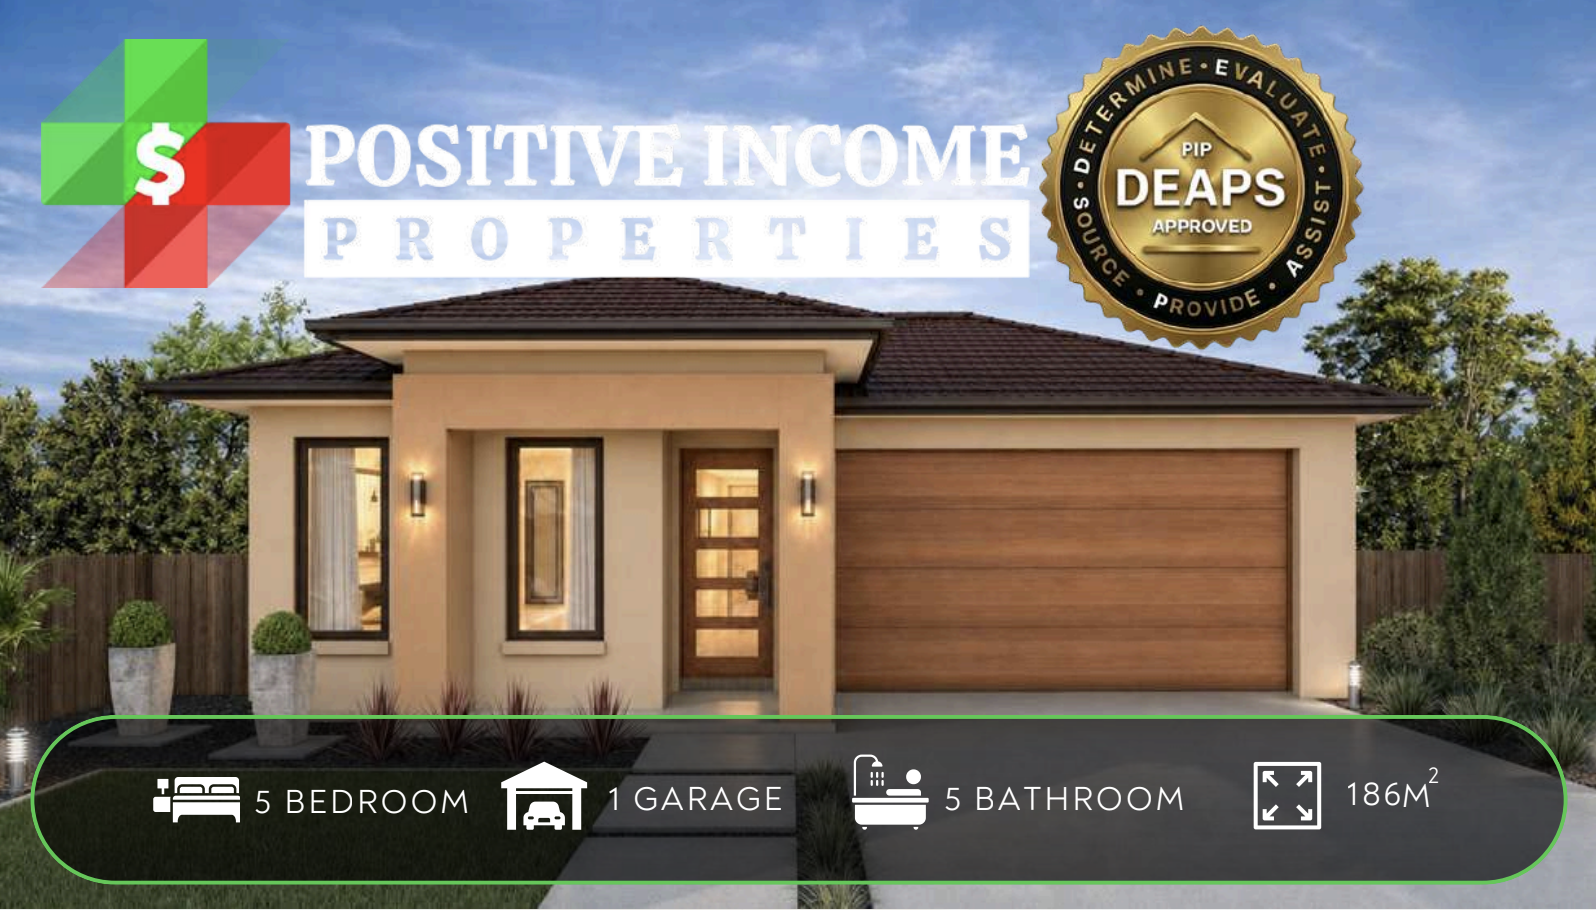
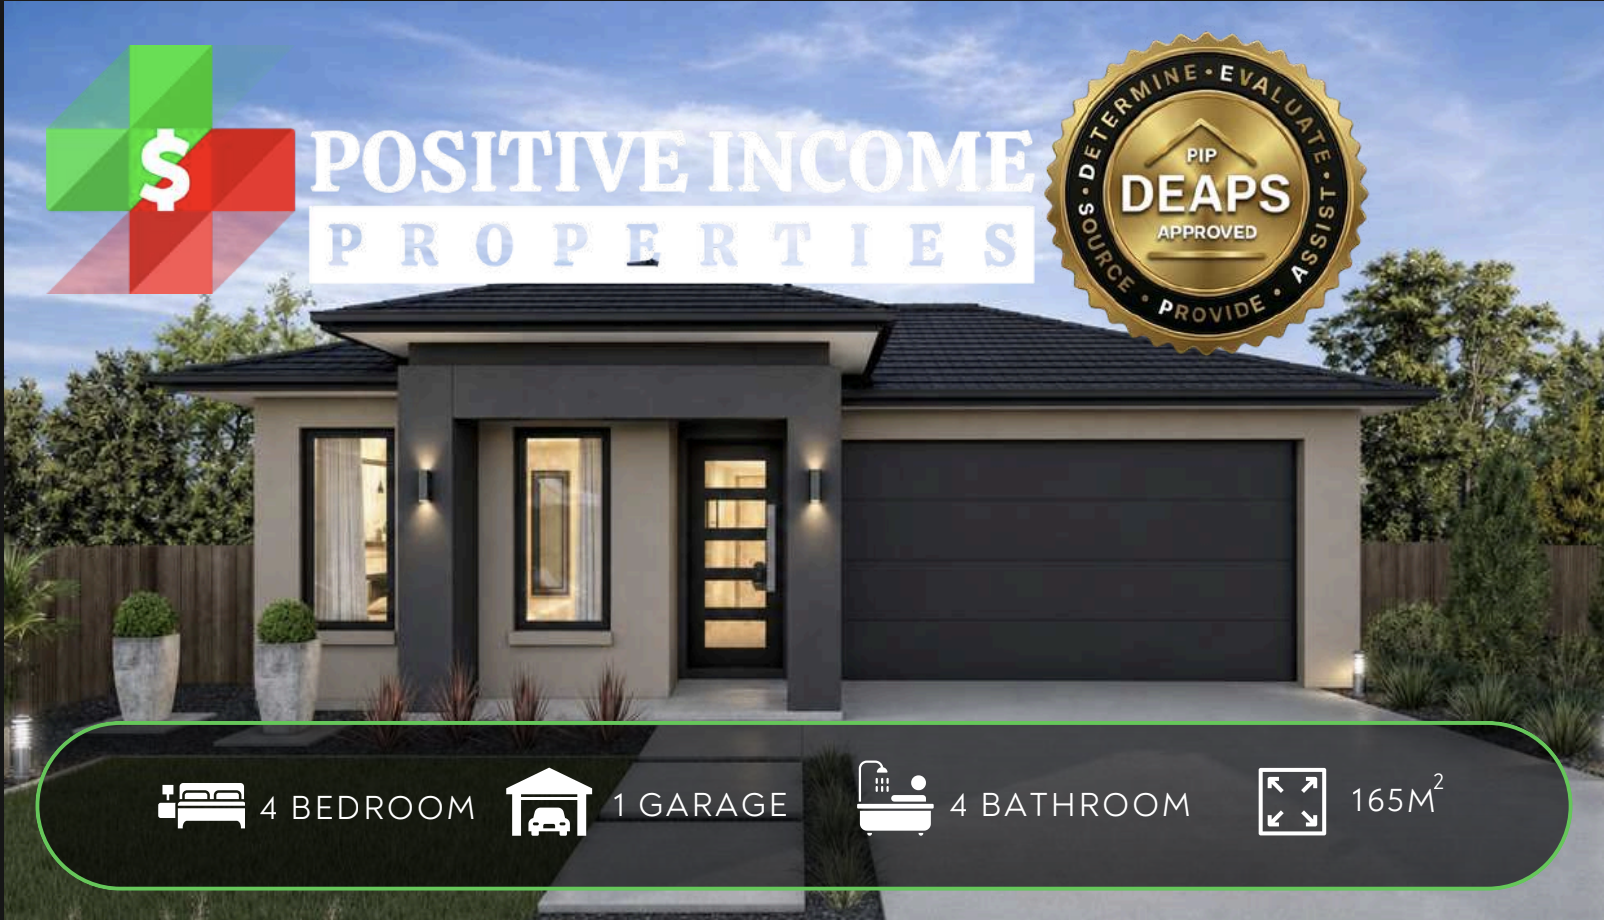
All four are at Uptown Estate, Shepparton VIC 3631, with the land registered, and each carries the builder’s 75% five-year rental guarantee (terms and eligibility apply). Yields are gross and every figure is an estimate and depends on the market, the tenancy mix and your costs. Ask us for the full cash flow, after every cost, on any of them.
Want to see a property that runs at a profit from settlement? We can walk through the numbers with you, calmly.
Book a quick callPositive Cash Flow FAQs
What is a positively geared property?
A positively geared property earns more in rent than it costs to hold, so it makes a profit each year rather than a loss. After the loan interest, rates, insurance, management and upkeep are paid, there is money left over, and that positive cash flow goes to you.
Is positive or negative gearing better?
Neither is better in every market. Negative gearing suits fast-growing markets, where a small yearly loss is offset by strong capital growth. Positive gearing suits markets like 2026, where growth is slower and reliable income matters more. Many investors aim for cash flow first, then growth on top.
Do you pay tax on a positively geared property?
Yes. Because a positively geared property makes a profit, you pay tax on that profit at your marginal rate. Deductions such as depreciation can reduce the taxable amount, especially on a new build, so the after-tax result is often better than the raw numbers suggest. Please seek advice from an accountant on your own situation.
What is a good positive cash flow?
There is no single figure, because it depends on your goals and the property price. As a rough guide, a gross yield above roughly 6% is where a property tends to cover its own costs, and dual-income or co-living layouts can push well past that. The figure that matters is the rent left over after every cost.
How Positive Income Properties Helps You Find Positive Cash Flow
Positive Income Properties researches and supplies pre-packaged, brand-new investment properties in locations with genuine rental demand. To find where the numbers work, we assess employment growth, infrastructure pipelines, population forecasts and rental performance, and we favour layouts that earn more from the same block. Our investors gain access to more than 1,600 positive cash flow investment properties, and many return as their portfolios grow.
So before you judge a property on its asking price, the smart step is to see its real cash flow, after every cost, on paper.
See a positive cash flow property that suits your budget and goals. A quick call is the easiest place to start.
Book a quick callTo talk through what a positively geared property could mean for your situation, you can also contact Positive Income Properties on +61 468 037 484 or bookings@positiveincome.com.au.
Disclaimer: This article is general information only. It is not tax, legal or financial advice. Return and yield figures are estimates, not guarantees, and depend on market conditions. Any rental guarantee is provided by the builder or developer under its own terms, conditions and eligibility, for a limited period. The 2026 Budget measures referenced are proposed and not yet law; detail and timing may change. Positive Income Properties is not a financial adviser. Please seek independent legal, financial and taxation advice before making any investment decision.
Author: Gil Elliott, Managing Director and Founder of Positive Income Properties, with nearly four decades of experience across the real estate and marketing industries.

Gil Elliott is the Managing Director and Founder of Positive Income Properties. Gil has a rich background in business consulting and property investment. All of these he gained in his nearly four decades of experience in the real estate and marketing industries.


